Tax Efficiency and Asset Protection Explained
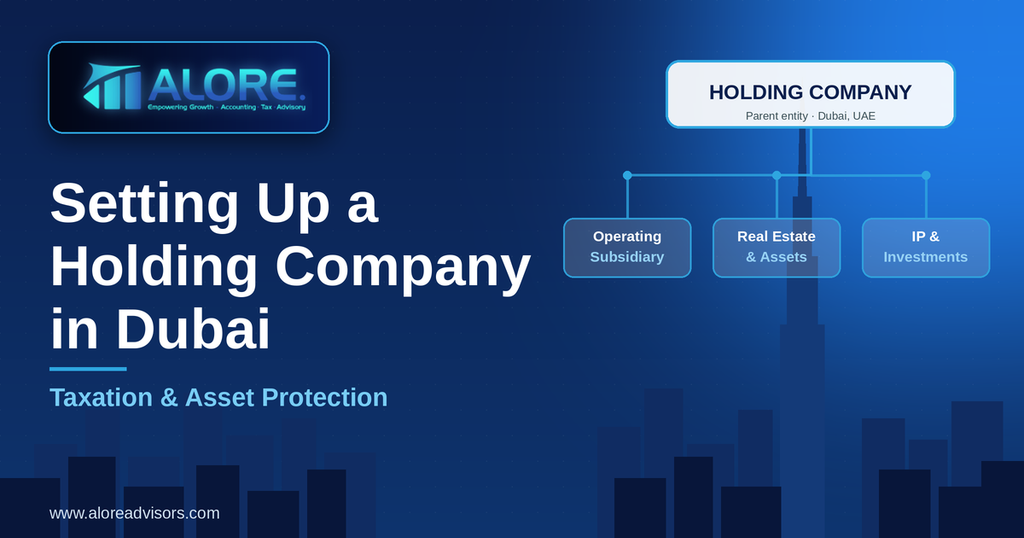
Anyone building a corporate structure in the UAE has to weigh two goals at once: keeping the tax position efficient and keeping assets safe. A holding company is one of the most widely used vehicles for achieving both. It lets a family or a business group bring its subsidiaries, investments, property and intellectual property under a single parent entity. This guide walks through the legal basis, the tax advantages, the setup steps and the protective benefits of a Dubai holding company.
1. Which Laws Govern a Holding Company?
Two pieces of federal legislation form the backbone of any holding structure in the UAE.
- Federal Decree-Law No. 32 of 2021 (Commercial Companies). This is the main law governing how companies are formed and run across the country. Federal Decree-Law No. 20 of 2025 amended it to permit multiple share classes and to make it easier for companies to change their place of registration.
- Federal Decree-Law No. 47 of 2022 (Corporate Tax). This law sets out how businesses are taxed and is the source of the exemptions that holding companies rely on, provided the stated conditions are met.
For verified, current copies of these laws, the UAE Legislation Portal is the official source, while the Ministry of Economy oversees company registry rules, licensing guidelines and foreign investment policy. Reading the commercial and tax rules together at the formation stage helps ensure the parent entity is properly recognised and compliant from the start, whether it is set up on the mainland, in a free zone or offshore.
2. How a Holding Company Becomes Tax Efficient
UAE corporate tax planning gives qualifying holding companies access to specific exemptions, as long as they meet every condition in the law.
- The participation exemption. Articles 22 and 23 of Federal Decree-Law No. 47 of 2022 allow a qualifying holding company to exclude certain dividend income, as well as gains or losses on a qualifying participation, from taxable income.
- The conditions. Article 23 lists several tests that must all be satisfied. These include a minimum ownership level (or a prescribed acquisition cost), a holding-period requirement, a subject-to-tax condition, entitlement to profits and liquidation proceeds, and an asset-composition test.
- The 12-month holding period. Under Article 23(2)(a), the parent must have held the participation, or intend to hold it, without interruption for at least 12 months.
- The subject-to-tax condition. The investee must meet the subject-to-tax test set by the Corporate Tax Law and its implementing decisions. This should be reviewed alongside the other conditions before the exemption is claimed.
- Withholding tax. Article 45 provides the withholding tax framework. At present the rate is 0%, although a future Cabinet decision could set a different rate or apply it to particular categories of income.
3. Steps to Set Up a Compliant Holding Company
Whether you choose a mainland, free zone or offshore route, the process involves formal registration and alignment with the relevant regulator.
- Choose the jurisdiction. A holding company can be formed on the mainland, in an eligible free zone (for example DIFC, DMCC, ADGM, RAKEZ and others that allow holding activities) or in an offshore jurisdiction, depending on your objectives and the rules that apply.
- Prepare the constitutional documents. The licensing authority will expect a Memorandum of Association that clearly states the company exists to hold shares, real estate or other assets.
- Register for Corporate Tax. Under Cabinet Decision No. 10 of 2024 and FTA Decision No. 3 of 2024, a holding company that must register needs a Tax Registration Number (TRN) from the EmaraTax portal. The deadline depends on the licence issue date or the date of incorporation or recognition, and late registration can attract administrative penalties.
- File an annual return. A holding company must submit a corporate tax return within nine months of the end of its tax period, even if it has no taxable income.
- Mind the penalty for late registration. A fixed administrative penalty of AED 10,000 applies when the registration deadline is missed. Recent changes to the penalty framework were introduced to avoid compounding fines, so the current rules should be confirmed at the time of registration.
4. How a Holding Structure Protects Your Assets
A well-designed holding structure can reduce exposure to operational and legal risk.
- Separating risk. Because ownership of assets sits apart from the day-to-day activities of the operating subsidiaries, a problem in one business is less likely to reach the rest. This is subject to applicable laws, guarantees, contractual commitments, regulatory requirements and insolvency rules.
- Centralising intellectual property. Trademarks, patents and real estate can be held by the parent and licensed or leased to the operating companies.
- Flexible share classes. Following the 2025 amendments, mainland and free zone holding companies can issue different share classes, allowing voting rights to be set independently of capital contributed.
- Support for succession planning. The company’s constitutional documents can include mechanisms for transferring ownership, subject to company law, inheritance rules and free zone regulations.
- Greater corporate mobility. The 2025 changes also make it possible for eligible companies to move their registration, provided the required procedures, approvals and licensing authority conditions are met.
5. A Common Pitfall to Avoid
One mistake we see often is the assumption that the participation exemption applies automatically once the 12-month holding period has passed. In reality, the subject-to-tax condition and the asset-composition test must also be satisfied. A structure that looks sound on paper can fail one of these tests in practice, which is why a review before formation is usually far cheaper than a correction after the return has been filed.
Substance is another point worth checking. Most holding companies can use a registered agent’s address or a shared desk for their legal address, but they still need to meet the substance requirements that apply under UAE Corporate Tax Law.
6. Frequently Asked Questions
Does a holding company have to file an annual corporate tax return?
Yes. Every registered legal entity is a taxable person under Federal Decree-Law No. 47 of 2022. The company must register and file its return through EmaraTax within nine months of its financial year-end, even when all of its income qualifies for the 0% rate.
What happens if the company registers late?
- The FTA issues a fixed administrative penalty, currently AED 10,000.
- Registration should be completed promptly and the penalty settled according to FTA procedures.
- A delay can also create practical difficulties when filing returns, keeping corporate records or answering FTA queries.
Can a holding company own real estate in the UAE?
Yes, subject to the rules of the relevant Emirate’s land department. Holding property through a company adds a layer of protection and can make future ownership transfers simpler.
Does a holding company need a physical office?
Usually not. Many free zone and offshore holding structures use a registered agent’s office or a shared desk as their legal address, provided the substance requirements under the Corporate Tax Law are still met.
What shareholding is needed to claim the participation exemption?
- The holding must meet the ownership or other qualifying threshold set under Article 23 and its implementing decisions.
- The interest generally has to be held, or be intended to be held, for an uninterrupted 12 months.
- The subject-to-tax condition, profit and liquidation entitlement, asset-composition test and any other prescribed conditions must also be satisfied.
How ALORE Advisors Can Help
Structuring a holding company correctly takes both local knowledge and a clear understanding of how the UAE tax rules keep changing. ALORE Advisors can help with:
- Choosing the right jurisdiction and designing a structure around your wealth-management and asset-protection goals
- Reviewing eligibility for the participation exemption before you invest, not after you file
- Corporate Tax registration on EmaraTax, bookkeeping and annual return filing
- Ongoing compliance support to avoid administrative penalties
Disclaimer:
The content of this guide is intended as general information and should not be treated as tax or legal advice. Whether any exemption applies, including the participation exemption under Article 23 of Federal Decree-Law No. 47 of 2022, turns on the particular circumstances and ownership structure of each company, and on every required condition being met. Before acting on anything in this guide for a specific transaction or structure, please seek advice from a qualified tax professional.
Alore Advisors | Accounting, Tax and Business Advisory