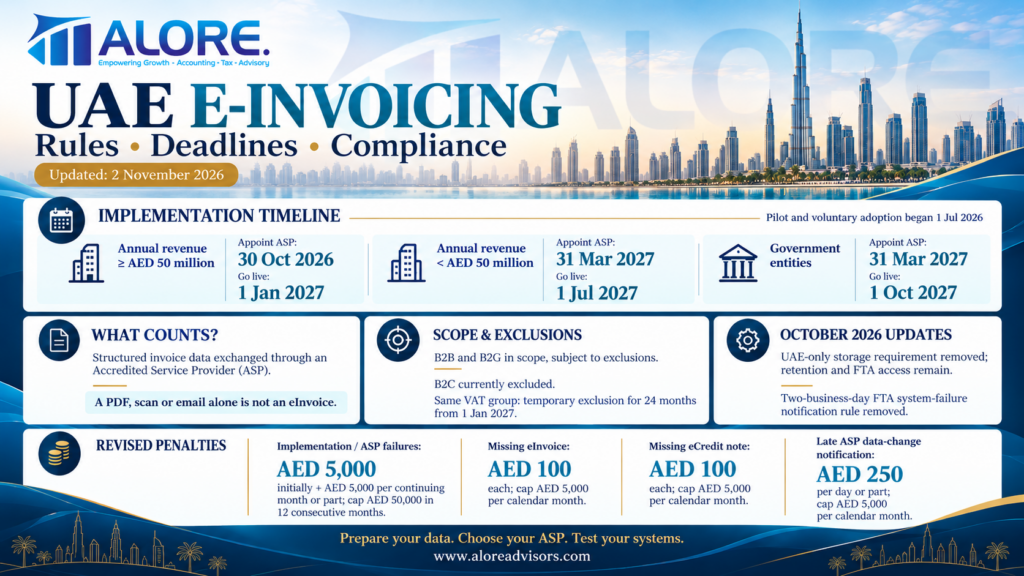
The UAE is moving towards structured electronic invoicing, with mandatory implementation beginning in phases in 2027. Businesses need to prepare their accounting data, select an Accredited Service Provider (ASP), and test invoice exchange and reporting before their applicable deadline. The framework was updated in October 2026, making some earlier guidance and penalty summaries outdated.
What Is UAE E-Invoicing?
An e-invoice contains structured data that systems can process automatically. It is exchanged electronically between supplier and buyer, with relevant tax data reported to the Federal Tax Authority (FTA). An invoice sent as a PDF, Word document, image, scan or email alone does not meet this definition. Producing an attractive digital invoice is therefore only one part of preparing for compliance.
Source: Ministry of Finance eInvoicing portal.
UAE E-Invoicing Implementation Dates
| Category | Deadline to appoint an ASP | Mandatory implementation |
| Annual revenue of AED 50 million or more | 30 October 2026 | 1 January 2027 |
| Annual revenue below AED 50 million | 31 March 2027 | 1 July 2027 |
| Government entities | 31 March 2027 | 1 October 2027 |
The pilot programme and voluntary implementation began on 1 July 2026. The original large-business ASP appointment deadline of 31 July 2026 was extended to 30 October 2026; the January 2027 implementation date was unchanged. As at this article’s date, that ASP appointment deadline has passed. Businesses in this category that have not appointed a provider should address this immediately.
Sources: FTA deadline announcement; MD 244 of 2025, as amended.
Who Must Comply with UAE E-Invoicing Rules?
The scope extends to persons conducting business in the UAE, regardless of VAT registration, subject to exclusions and phased commencement. Business-to-business and business-to-government transactions are covered. A business should not assume it is exempt simply because it is small, operates in a free zone or is not registered for VAT.
Business-to-consumer transactions remain outside mandatory implementation until a further ministerial decision. A business with both business and consumer customers should classify its transactions separately. Relevant non-resident suppliers can also be affected where UAE VAT law requires them to issue tax invoices.
Source: Official guidelines, scope provisions; read with subsequent amendments.
How Does E-Invoice Sync and Reporting Work?
The UAE uses a five-corner model. The supplier submits invoice data to its ASP, which validates it, converts it to the required XML format where necessary, and transmits it to the buyer’s ASP. Tax data is reported to the FTA in parallel. The buyer’s ASP validates the invoice, delivers it to the buyer, and reports tax data following successful validation. Electronic confirmations identify successful processing or failures.
This requires monitoring of delivery and reporting statuses. Saving an invoice in accounting software does not by itself demonstrate successful exchange.
The October 2026 guidelines require one ASP per person. The participant identifier uses the entity’s 10-digit TIN, with identifier scheme 0235. Revenue means gross income for the latest accounting period. The guidelines also say newly established persons in scope must appoint an ASP and complete onboarding before their first invoice; new businesses should confirm their onboarding treatment promptly.
Source: UAE Electronic Invoicing Guidelines V2.0, 26 October 2026.
Required Information for Electronic Invoices
Data mapping should cover invoice number, date, type and currency; supplier and buyer identification and addresses; electronic identifiers; payment information; line descriptions, quantities, units and prices; tax categories and rates; and document totals. Transaction-specific fields must reflect the actual supply.
Businesses should use the current Ministry mandatory-field specification and PINT-AE rules with their ASP. A supplier name and total amount alone are insufficient for structured validation. Master-data checks should start before integration testing.
Sources: MoF mandatory-field requirements; official field guidance.
Invoice Issuance, Corrections and Data Update Deadlines
VAT registrants must follow the issuance and transmission timelines prescribed by VAT law. Subject to that rule, the amended general deadline is 14 business days from the Date of Business Transaction, rather than 14 calendar days. That transaction date is the earlier of the transaction occurring or payment being received. The general business-day rule should not be treated as an extension of a VAT deadline.
An electronic credit note is required for cancellation, reduced consideration, full or partial refunds, or administrative or numerical errors, as applicable. Corrections should preserve a traceable record. Agents may invoice on behalf of principals, and self-billing is permitted subject to the prescribed conditions.
Issuers and recipients must notify their ASP in writing of changes to FTA-registered data within five business days after receiving the FTA’s amendment confirmation.
Sources: MD 243 of 2025, Articles 1, 5, 6, 8 and 9; MD 197 of 2026.
E-Invoicing Exclusions and October 2026 Updates
Specific exclusions cover sovereign government activities outside private-sector competition; qualifying international airline passenger and ancillary services; qualifying airline goods transport supported by an airway bill, temporarily; and specified financial services. These conditions must be checked transaction by transaction: an exclusion for airlines does not exempt all freight or shipping businesses, and zero-rated treatment does not automatically create an exclusion.
Transactions between members of the same VAT tax group have a temporary 24-month exclusion starting 1 January 2027. Common ownership alone does not establish eligibility. External transactions remain subject to the normal rules.
The October amendments removed the requirement to store e-invoice data specifically within the UAE. Retention and the ability to produce records to the FTA remain mandatory. They also removed the specific requirement to notify the FTA of a system failure within two business days. Businesses should still maintain incident logs, recovery arrangements and controls over unprocessed invoices.
Sources: MD 197 of 2026; MoF amendment announcement.
UAE E-Invoicing Penalties
Cabinet Decision 173 of 2026 replaces Decision 106 of 2025.
| Violation | Revised penalty |
| Failure to implement, including failure to appoint an ASP; specified continuing recipient non-compliance | AED 5,000 initially, plus AED 5,000 for each continuing month or part, capped at AED 50,000 in any 12 consecutive months |
| Failure to issue and transmit an e-invoice | AED 100 each, capped at AED 5,000 per calendar month |
| Failure to issue and transmit an electronic credit note | AED 100 each, capped at AED 5,000 per calendar month |
| Failure to notify the ASP of FTA-registered data changes | AED 250 per day or part, capped at AED 5,000 per calendar month |
Voluntary participation is excluded from this decision’s penalties. Existing VAT and tax-procedure obligations must still be considered. The previous system-failure notification penalty has been removed.
Sources: Cabinet Decision 173 of 2026; MoF revised-penalty announcement.
How to Prepare Your Business for E-Invoicing
Assign an internal owner and confirm scope and deadlines. Compare accredited providers on integration, support, archival access and total cost. Clean customer and supplier records, map invoice fields and tax treatments, and test invoices, credit notes, rejected messages and recovery procedures. Agree who monitors failures and reconcile exchanged invoices to the sales ledger and tax records.
These are recommended implementation controls. Each business should document how its own software, branches and transaction types will meet the legal requirements.
Alore Advisors | Accounting, Tax and Business Advisory
This article summarises the UAE framework as at 2 November 2026. Sector-specific scenarios and technical configurations should be checked against current legislation and official specifications.