Ownership benefits and tax and compliance requirements | Alore Advisors
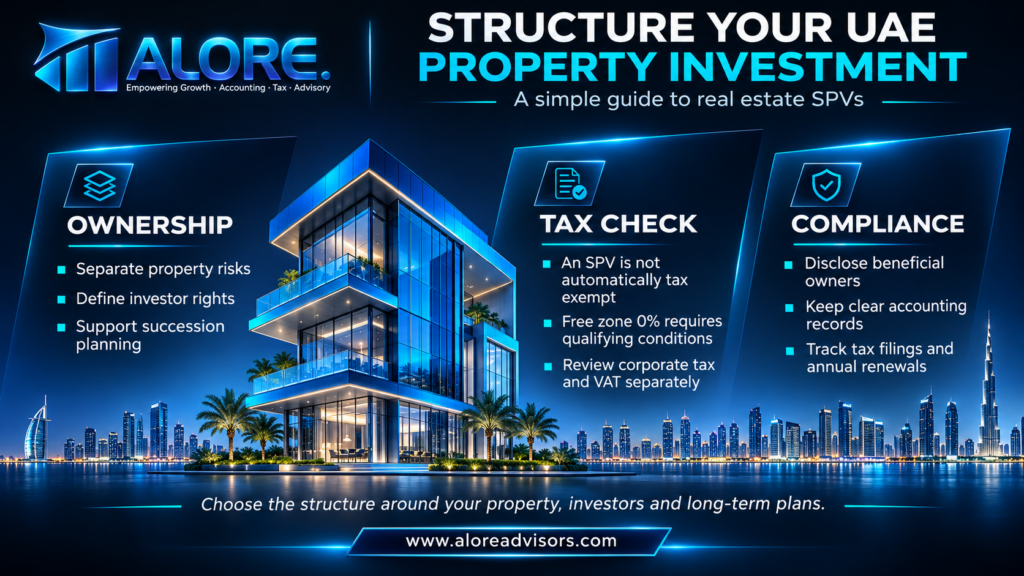
An SPV can help you organise a property investment and agree how investors will manage it. This guide explains the main benefits, setup steps and ongoing duties in simple language. An SPV does not automatically give you a tax exemption.
What is an SPV
SPV means Special Purpose Vehicle. It is a company that holds a particular asset or serves a specific purpose. For example, investors may create one company to own a building. The company owns the building, while the investors own shares in the company.
- One SPV may hold one property or a defined group of investments.
- The company keeps its own bank transactions, contracts and accounting records.
- A passive holding company holds investments. Its licence may restrict active business activities. ADGM SPVs cannot conduct operational business or hire staff. [1]
Why property investors use an SPV
An SPV gives investors a clear ownership framework. It can also help separate the risks of one investment from other assets, depending on the law and the contracts involved.
- Separate risks: use a dedicated company for a particular property.
- Agree control: record who can approve borrowing, spending and a sale.
- Share returns: set each investor’s ownership and profit distribution rights.
- Plan succession: coordinate company shares with family estate planning.
- Prepare for finance or sale: keep a clear record of ownership and funding.
Example: Two investors hold shares in a company that owns a rental building. Their agreement sets out who manages the investment and how they divide profits. The company records the rent and property expenses.
Understand the limits of protection
An SPV cannot protect you from every claim. A personal guarantee may expose your own assets. Guarantees between companies can also connect risks that you intended to keep separate.
- Keep the company’s money separate from personal money.
- Review loan guarantees and security before signing.
- Ask a legal adviser to review the ownership and liability arrangements.
Understand corporate tax and VAT
An SPV can have corporate tax obligations
A UAE company generally falls within corporate tax unless a specific exemption applies. Under the standard tax regime, the tax calculation uses taxable income after the required adjustments. Gross rent is not the same as taxable income. [2]
| Taxable income under the standard regime | Rate |
| Up to AED 375,000 | 0% |
| Amount above AED 375,000 | 9% |
Passive ownership and an SPV licence do not automatically remove registration or filing duties.
Free zone registration does not guarantee 0% tax
A Qualifying Free Zone Person can apply 0% to Qualifying Income only if it meets the relevant conditions. Property income needs a separate review. The rules look at the type of property, its location and the other party to the transaction. [3]
- Check whether the property is commercial or residential.
- Check whether it sits inside a free zone and whether the other party is a Free Zone Person.
- Meet the applicable substance and transfer pricing conditions.
- Review non-qualifying income and the relevant limits carefully.
Certain commercial property income within a free zone may qualify when the transaction involves another Free Zone Person. Other property income can attract 9%. Do not automatically apply the standard AED 375,000 band to income taxed under the special qualifying free zone rules. [3]
Property income and share income follow different rules
Certain dividends and gains from qualifying share investments can receive exemptions. These exemptions do not automatically cover rent or profit from selling a building. Check the conditions for each type of income. [2]
Compare company ownership with personal ownership
An individual’s property investment income earned in a personal capacity generally falls outside corporate tax. A company does not receive the same treatment automatically. Compare the costs and tax outcome before transferring a personally owned property into an SPV. [4]
Check VAT separately
VAT depends on the property and the transaction. Corporate tax treatment does not decide VAT treatment. [5]
| Property or issue | General VAT treatment |
| Commercial property supplies | 5% VAT |
| Residential supplies | Generally exempt |
| First residential supply within three years of completion | Can qualify for 0%, subject to the rules |
| Registration and expense recovery | Review separately, including mixed-use property costs |
Choose a structure and set up the company
Choose the jurisdiction for your investment
The right jurisdiction depends on the property, shareholders, financing and ongoing costs. Confirm that the land registry will accept the proposed company as owner before you pay for incorporation.
- ADGM offers passive SPVs. Non-exempt SPVs must appoint an ADGM licensed Company Service Provider. [1, 6]
- DIFC calls its SPVs Prescribed Companies. Its official information states that the 2026 changes opened the regime to any applicant, subject to the applicable requirements. [7]
- For DMCC or another free zone, verify the legal form and permitted holding activity. The same SPV rules do not apply everywhere.
Follow these setup steps
Plan the ownership and funding first. This helps you avoid creating a company that cannot hold your chosen property or meet your investment needs.
- Define the purpose: identify the property, investors and intended holding period.
- Check property eligibility: confirm ownership areas, registry acceptance and transfer approvals.
- Compare jurisdictions: review legal requirements, banking, providers and annual costs.
- Prepare documents: gather passports, address evidence, ownership charts, shareholder documents and funding evidence.
- Agree investor rights: document voting, profit sharing, borrowing and exit arrangements.
- Register the company: complete incorporation and applicable beneficial ownership disclosures.
- Arrange banking: provide the information the bank requests. Registration does not guarantee an account.
- Set up compliance: review corporate tax and VAT obligations and start the accounting records.
Budget for setup and annual costs
The initial registration fee covers only part of the cost. Ask for a quotation that separates one-time charges from recurring expenses.
| Cost category | What to include |
| Setup | Incorporation, documents and professional assistance |
| Annual | Renewal, registered office and required service provider fees |
| Reporting | Bookkeeping, tax work and audit where required |
| Property transactions | Valuation, registration, transfer and financing costs where applicable |
Keep the SPV compliant
Disclose the real owners and explain the funding
The ultimate beneficial owners are the people who ultimately own or control the company. Keep their information current under the rules of the chosen jurisdiction. Banks and professional providers may also ask where the investment money came from.
- Maintain an accurate ownership chart and beneficial owner information.
- Keep evidence of the source of funds and source of wealth when required.
- Cooperate with due diligence requests from banks and other relevant parties.
AML means anti-money laundering. An SPV’s direct AML duties depend on its activities. Passive ownership alone does not automatically make it a regulated property broker or a designated non-financial business. Check which duties apply to the actual business.
Keep records and track deadlines
Good records show what the company owns, earns, spends and owes. They also support tax returns and help investors monitor performance.
| Compliance area | Action or timing |
| Accounting | Record rent, expenses, purchases, borrowing and shareholder balances for each company |
| Supporting documents | Keep titles, leases, invoices, bank statements and tax calculations |
| Corporate tax records | Retain for at least seven years after the relevant tax period [8] |
| Corporate tax return and payment | Generally within nine months after the tax period ends [8] |
| Company filings | Track renewal, annual returns, owner updates and accounts or audit requirements separately |
Understand the ESR change
ESR means Economic Substance Regulations. The UAE ended ESR notifications and reports for financial years ending after 31 December 2022. Earlier obligations can still apply. [9]
- Do not treat ESR reporting as a routine current-year filing requirement.
- Continue to meet any substance conditions that apply under corporate tax or other rules. [3]
Plan how investors will leave
Investors may sell the property or sell shares in the company. Each option can have different approvals, taxes and costs. A share sale does not automatically avoid property-related fees.
- Check land registry requirements and lender consent.
- Review change of control clauses and the tax outcome.
- Agree how investors will value shares and resolve disputes.
Speak to Alore Advisors
Contact Alore Advisors to discuss the accounting and tax implications of your proposed property structure and its ongoing compliance requirements.
General information only. Obtain advice for your specific property and ownership arrangements before acting.
Disclaimer:
This article is intended as general information, not legal advice or a formal compliance opinion.
Alore Advisors | Accounting, Tax and Business Advisory